IFRS 9 ECL.
Lifetime losses, staged and forward-looking.
Point-in-time PD, LGD and EAD term structures, staging criteria and probability-weighted macro scenarios, with every overlay approved and traceable.
Reuse what your IRB models know. Make it point-in-time and forward-looking.
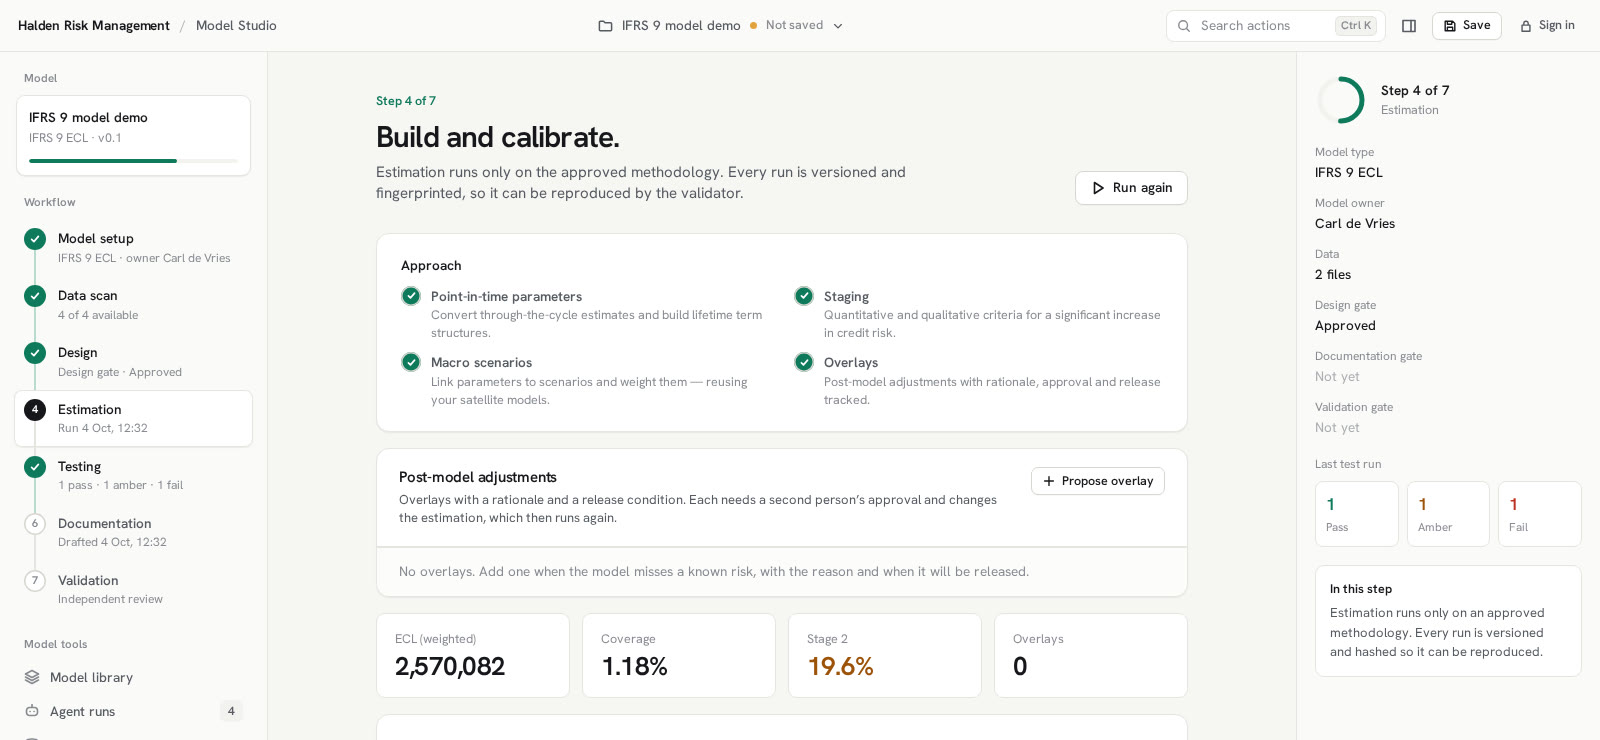
Point-in-time parameters
Convert through-the-cycle estimates and build lifetime term structures.
Staging
Quantitative and qualitative criteria for a significant increase in credit risk.
Macro scenarios
Link parameters to scenarios and weight them, reusing your satellite models.
Overlays
Post-model adjustments with rationale, approval and release tracked.
What you need. And what happens if you don't have it.
| Data | Needed | If missing or incomplete |
|---|---|---|
| Origination rating or PD | Required | Proxy at transition date, documented |
| Contractual cash flows | Required | — |
| Macro forecasts | Required | Official or bank-internal scenarios |
| Forbearance and watch-list flags | Helpful | Days-past-due backstop only |
Every choice is a decision for a person. Every test has its threshold on the page.
Each comes with a recommended option, the reason and any data gap. The model owner approves the set at the design gate.
- PIT conversionWhich asset correlation links PDs to the credit cycle?
- Scenario linkHow do scenario paths move PDs?
- Scenario weightsHow are scenarios weighted?
- ReversionAfter the scenario horizon, how fast do PDs revert to TTC?
- SICR · relative thresholdLifetime PD increase since origination that signals a significant increase in credit risk
- BackstopDays-past-due backstop for stage 2
Shown next to each result. A test outside its threshold stays visible and becomes a limitation in the documentation.
| Test | Group | Threshold |
|---|---|---|
| Staging stability and transfer rates | Staging | ≤ 10% of stage 1 moves |
| Back-testing of ECL against realised losses | Back-testing | Reported |
| Sensitivity to scenario weights | Scenarios | Reported |
| Overlay tracking and release | Overlays | Every overlay approved with a release condition |
| Reconciliation to the general ledger | Reconciliation | Reported |
Reviewing your ECL models?
See it done on your data.
We'll walk through your use case and show the product on data structured like yours.